The mortgage payment is only part of the budget. Here is what buyers should calculate before deciding what they can comfortably afford.
The purchase price does not tell you what owning a home will actually cost each month.
Your mortgage payment may include principal, interest, property taxes, homeowners insurance and mortgage insurance. You may also need to budget for association dues, utilities, maintenance and larger repairs.
I want buyers to understand the full cost before writing an offer. Qualifying for a loan and feeling comfortable with the payment are not always the same thing.
Principal and interest
Principal is the amount you borrowed. Interest is what the lender charges for the loan.
These amounts are based on your loan balance, interest rate and loan term. They usually make up the largest part of the payment, but they are not the entire cost of owning the home.
A mortgage calculator that shows only principal and interest can make a home appear more affordable than it is.
Property taxes
Property taxes vary by municipality, school district and property. Two similarly priced homes can have different tax bills depending on where they are located.
Your lender may collect part of the annual tax bill each month through an escrow account. If taxes are not escrowed, you will pay them separately. Either way, convert the annual tax bill into a monthly amount when comparing homes.
Taxes can change after closing. A higher assessment does not automatically create the same percentage increase in the tax bill, but buyers should not assume the current amount will remain fixed.
Homeowners insurance
Homeowners insurance is generally required when financing a home.
The cost depends on the property, coverage, deductible and insurer. The roof, electrical system, prior claims and other property-specific factors may affect the premium or availability of coverage.
Request an insurance quote during the transaction rather than relying on a general estimate. Depending on the property and location, additional coverage such as flood insurance may also be required or worth considering.
Mortgage insurance
A conventional loan with less than 20% down may require private mortgage insurance, or PMI.
PMI protects the lender, not the buyer. Its cost depends on the loan, down payment, credit and insurer.
A lower down payment can allow a buyer to purchase sooner or preserve more savings, but the mortgage insurance belongs in the monthly budget. Many conventional borrowers can eventually request its removal after reaching the required equity level and meeting the applicable conditions. FHA, VA and other loan programs follow different rules.
Condo and homeowners association dues
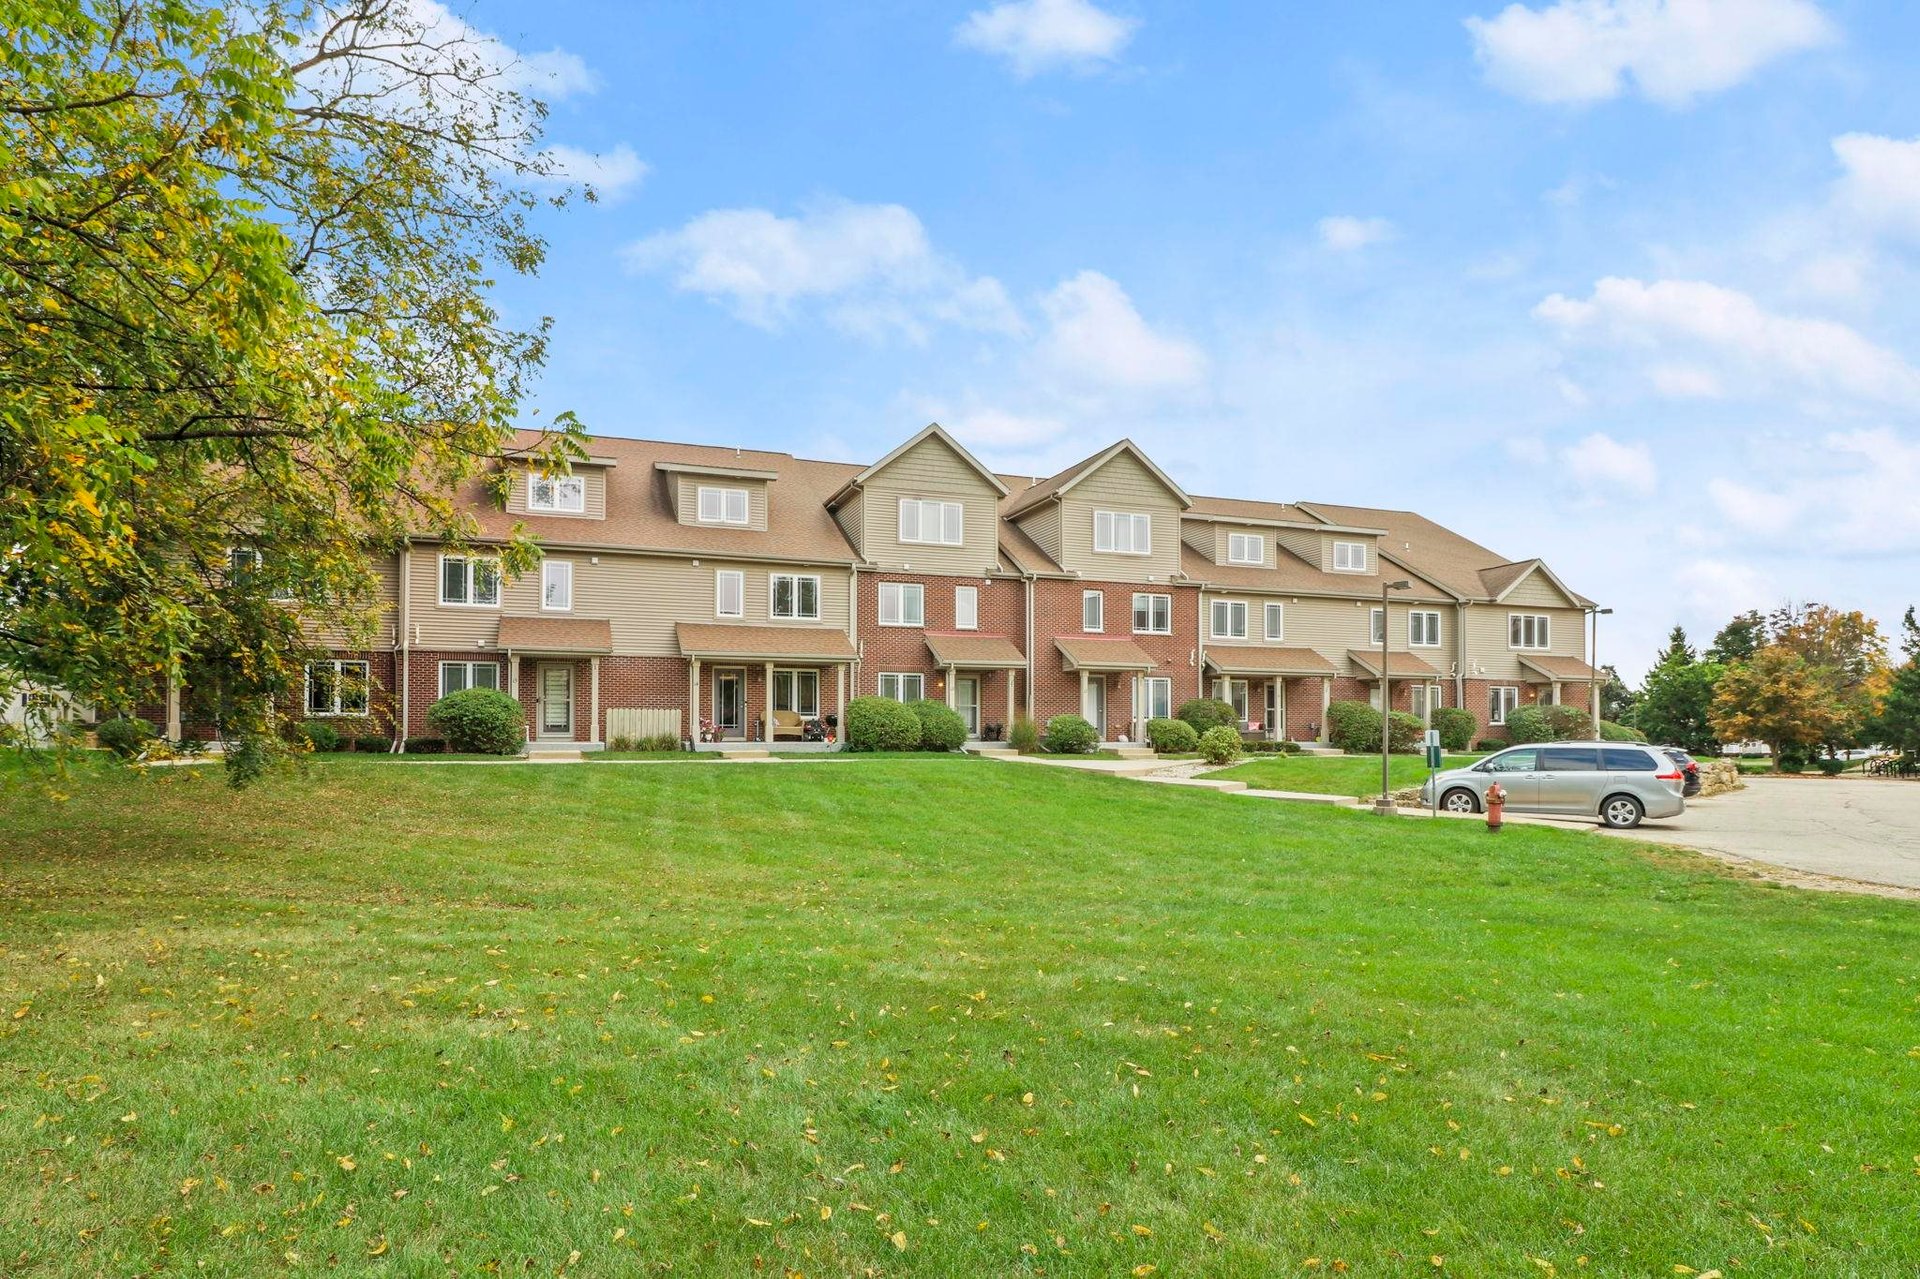
Condo or homeowners association dues are usually paid separately from the mortgage.
Review both the amount and what it covers. Dues may include exterior maintenance, insurance, snow removal, lawn care, water or shared amenities.
Also review the association’s reserves, planned projects and special assessments. A reasonable monthly fee does not necessarily mean the association is financially prepared for future repairs.
Utilities
Utility expenses depend on the home’s size, age, efficiency and systems.
Consider:
- Electricity
- Natural gas
- Water and sewer
- Internet
- Well, septic or water-softener expenses when applicable
Previous utility bills can provide context, but your costs may differ based on household size and how you use the home.
Maintenance and repairs
Maintenance is not part of the mortgage payment, but it belongs in the monthly budget.
Routine costs may include furnace servicing, gutter cleaning, landscaping, snow removal and appliance repairs. Larger expenses can include replacing a roof, furnace, air conditioner, windows or water heater.
Insurance generally does not cover an item simply because it is worn out. Look at the age and condition of the home’s major components and create a reserve that reflects that specific property.
Your total payment can change
A fixed-rate mortgage keeps the principal-and-interest portion predictable. It does not guarantee that your total payment will remain the same.
If property taxes or insurance premiums change, the amount collected through escrow may also change. Association dues, utilities and maintenance costs can increase as well.
Compare the total cost, not just the price
One home may have a lower price but higher taxes, association dues or expected maintenance. Another may cost more upfront but have newer mechanicals and fewer immediate repairs.
For each property, estimate:
- Principal and interest
- Property taxes
- Homeowners insurance
- Mortgage insurance, if applicable
- Association dues
- Utilities
- Routine maintenance
- A reserve for larger repairs
This gives you a more realistic picture of whether the home fits your budget.
The bottom line

The question is not simply, “What price am I approved for?”
The better question is, “What will this particular home cost me each month, and will I still feel comfortable after I move in?”
A lender can determine what you qualify to borrow. I can help you evaluate how the property itself affects the larger budget, including taxes, insurance, association costs, condition and upcoming maintenance.
The goal is not just to reach closing. It is to purchase a home you can comfortably own.
Planning a home purchase in the Madison area?
I can help you compare properties beyond the list price, identify costs that are easy to overlook and build a search around a monthly budget that feels right for you.
Check Our Home Buyer Resources
Explore Madison Homes for Sale
Schedule a Call with Cait
Sources:
Consumer Financial Protection Bureau: Principal and Interest vs. Total Monthly Payment
Consumer Financial Protection Bureau: Figure Out How Much You Want to Spend
Consumer Financial Protection Bureau: Private Mortgage Insurance
Consumer Financial Protection Bureau: Removing Private Mortgage Insurance
Wisconsin Office of the Commissioner of Insurance: Consumer’s Guide to Homeowners Insurance
City of Madison: Property Taxes